The roofing estimate describes the physical work
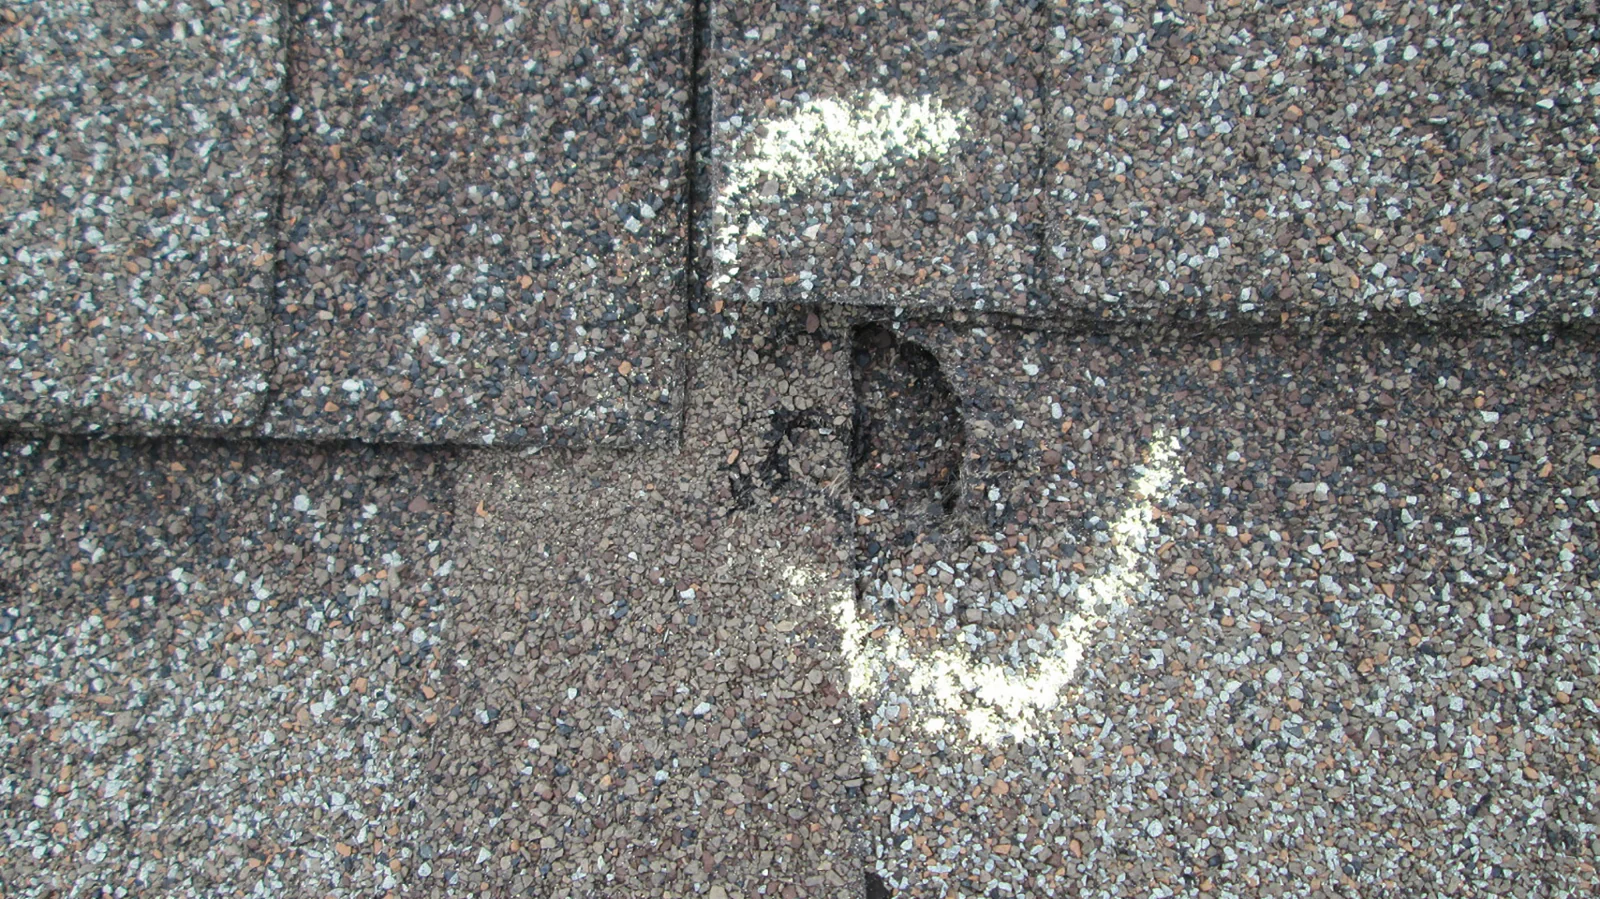
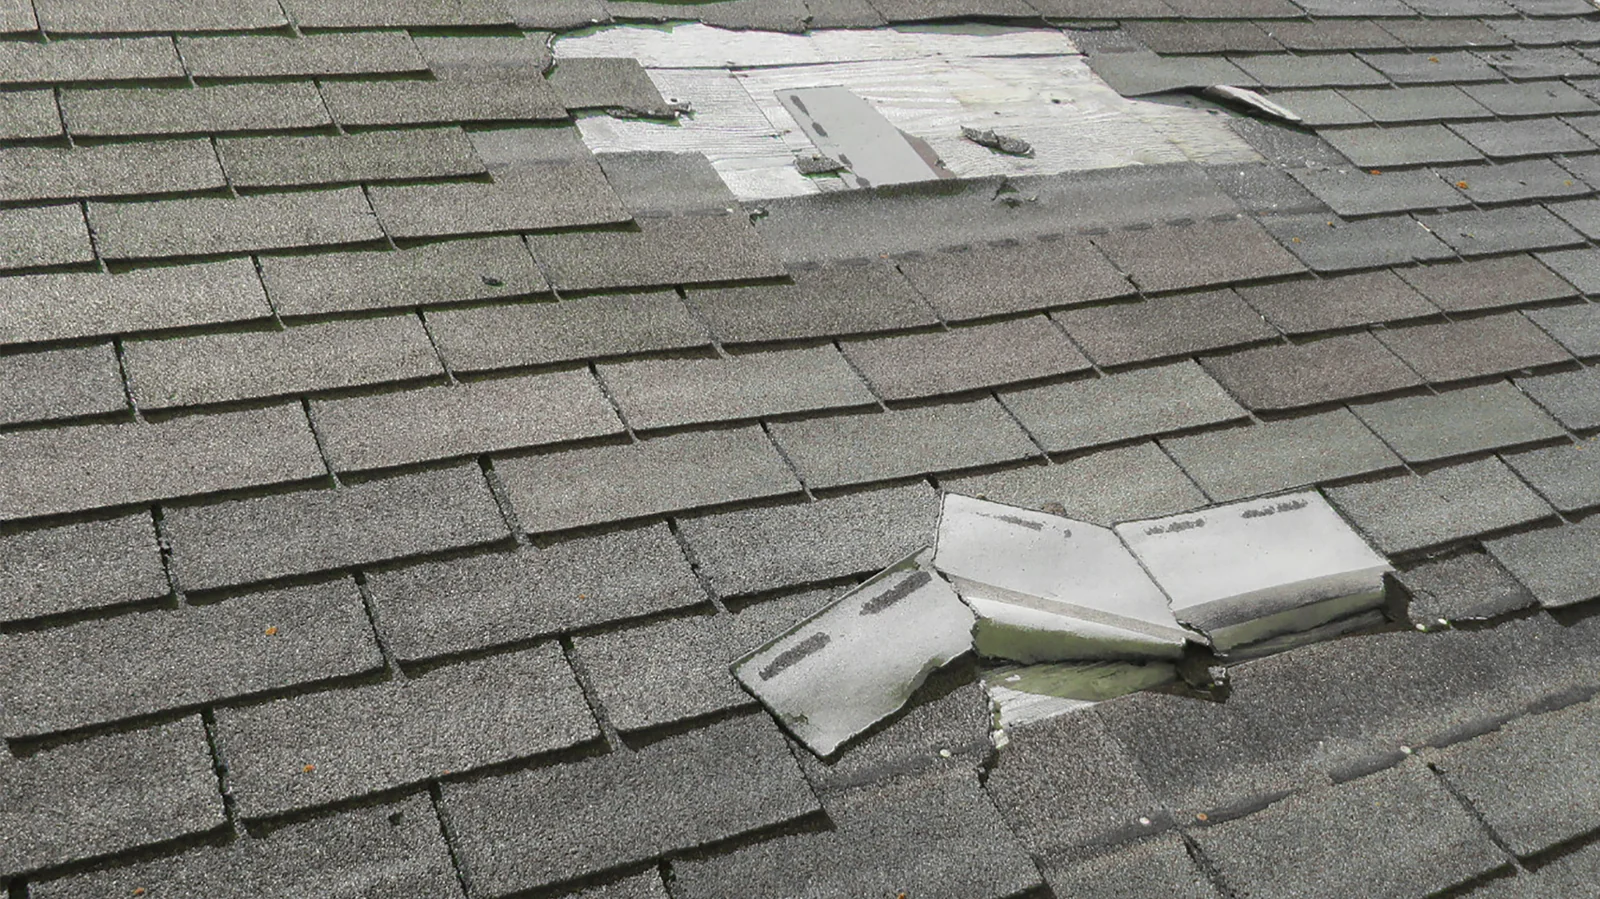
A contractor can inspect the roof, explain the damage it observes and prepare a price for repair or replacement. That estimate should describe the affected areas, materials and connected details.
A contractor may also answer an adjuster’s questions about the proposed construction. That does not make every roofer a licensed public adjuster or give the contractor control over the insurer’s coverage decision. Treat promises of automatic approval or a guaranteed payout with care.
The policy determines the payment
Covered causes of loss, exclusions, limits and deductibles differ. Roof age and condition can also interact with the policy’s settlement terms. A contractor cannot resolve those terms simply by calling a roof damaged.
Actual cash value generally reflects depreciation. Replacement-cost coverage can involve an initial payment and additional amounts after repair or replacement requirements are satisfied. The details, deadlines and documentation belong to the particular policy and claim, not to a universal roofing rule.
Understand the deductible before treating a roof as free
A wind or hail deductible can differ from another deductible in the same policy. A percentage deductible is calculated on the policy basis stated in the contract, not automatically as a percentage of the repair bill.
Oklahoma restricts roofing contractors from using a promise to pay or rebate the insurance deductible as an inducement. A legitimate construction agreement should show the price and the owner’s obligations plainly rather than hide them inside “free roof” language.
Keep the damage and repair record together
Safe photographs, the claimed event date, the contractor’s scope and any emergency-protection receipts help organize the claim. The insurer can explain what it needs before permanent work or disposal of damaged materials.
A temporary covering and a final replacement are different expenses and different stages. Do not delay necessary safety or damage-limitation measures just because the complete claim is unresolved, but keep their purpose and cost clear.
A disagreement needs the right next conversation
If the construction scope and the insurer’s estimate differ, identify the actual omitted or disputed work. A deck repair, flashing detail or code-related item is more concrete than a general argument that the payment is too low.
The insurer should explain its coverage and settlement position. Oklahoma Insurance Department consumer resources are available when a policyholder has questions about claim handling. A coverage or legal dispute may require a properly licensed professional; the directory does not decide claims.
Further reading
Common questions
Can a roofer guarantee my insurer will buy a new roof?
No. A roofer can describe damage and price the work. Coverage and claim payment depend on the insurer’s application of the policy and applicable rules.
Is replacement-cost coverage the same as receiving the entire price up front?
Not necessarily. The policy can provide an initial depreciated payment and additional payment after specified repair or replacement requirements are met.
Can a contractor waive the deductible?
Oklahoma restricts roofing contractors from offering to pay or rebate applicable deductibles as an inducement. The price and payment responsibilities should remain clear.
Find companies for the work.
Explore actual roofing services, business details and Google review totals in the directory.
Browse roofing companies